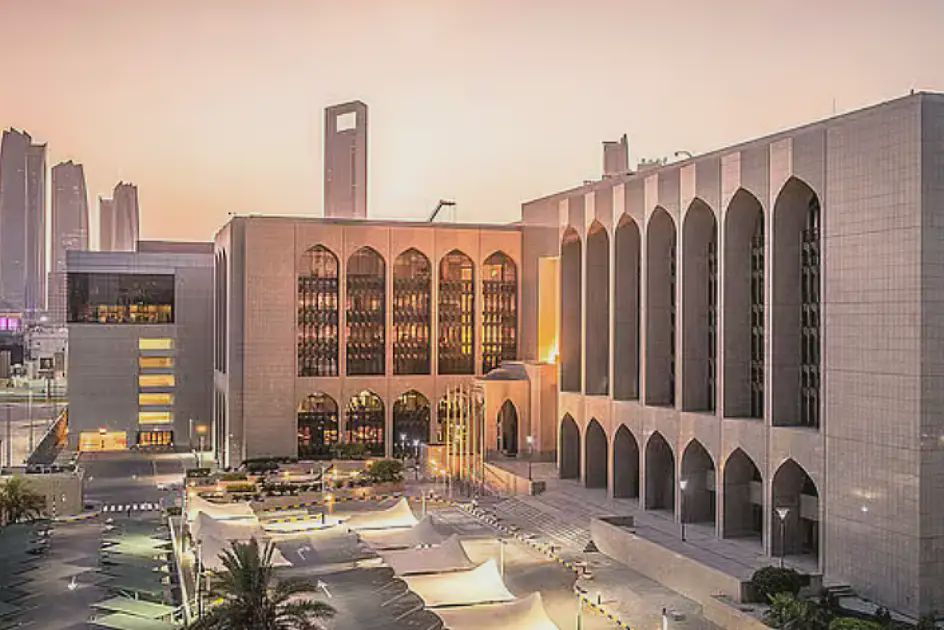
The Central Bank of the UAE (CBUAE) announced on Friday, October 30, 2026, that it had fined a branch of a foreign bank operating in the country Dh200 million for serious lapses in its anti-money laundering and counter-terrorism financing controls.
In its statement, the regulator said the bank showed "significant and repeated shortcomings" in implementing anti-money laundering safeguards and had also failed to properly uphold its governance and sanctions compliance framework. The CBUAE did not name the bank involved.
Beyond the institutional penalty, the central bank separately fined the branch's chief executive Dh500,000 and its head of compliance, who also serves as the money laundering reporting officer, Dh300,000. Banking analysts note that holding individual executives personally liable, rather than only the institution, signals a tougher enforcement posture from the regulator.
The CBUAE has ordered the bank to launch a full remediation programme, which must be independently reviewed and validated before it is considered complete. It has also required a fresh assessment of whether the chief executive and chief compliance officer remain fit to hold their positions.
"We will continue to ensure that banks, their senior decision-makers and employees comply with UAE laws and regulatory standards," the central bank said in its statement.
The penalty comes as the UAE continues to tighten financial oversight following its past inclusion on the Financial Action Task Force's grey list for anti-money laundering deficiencies. Since then, authorities have significantly increased enforcement actions against banks, exchange houses and other financial institutions operating in the country.
Compliance experts say the size of the fine, paired with personal penalties against senior bank officers, is likely to push other foreign banking branches in the UAE to review their own anti-money laundering procedures before they face similar scrutiny.